1. Understand What Pre-Approval Means
What is Mortgage Pre-Approval?
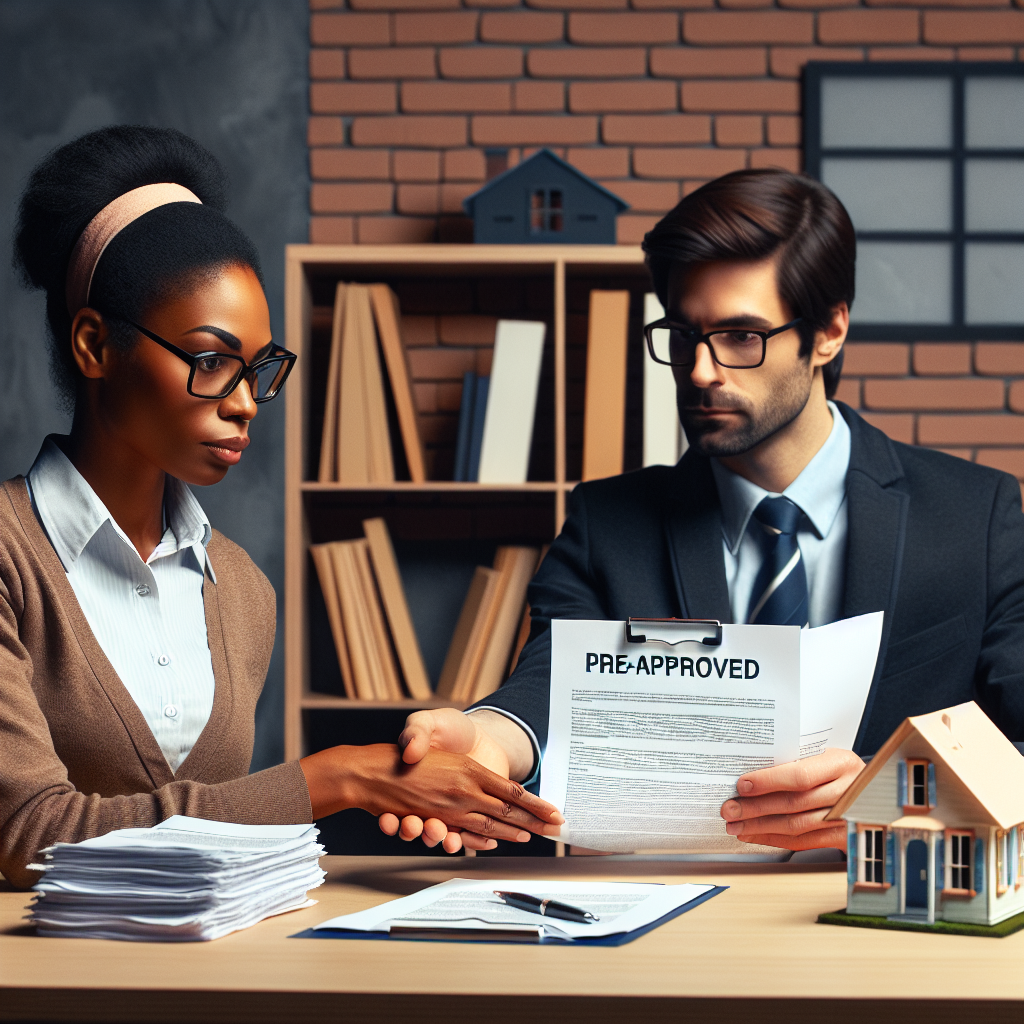
When I first heard about mortgage pre-approval, I thought it sounded pretty fancy. In simple terms, it’s when a lender checks your financial background to estimate how much they’d be willing to lend you. This isn’t just a casual guess either; it involves taking a good look at your finances, credit score, income, and debt. Think of it as getting a VIP pass into the world of home buying, telling sellers that you mean business.
For instance, my cousin went through this process before buying her first house. It gave her a clear picture of what she could afford, which was invaluable during her home search. Understanding this concept will help you feel more confident as you navigate the sometimes overwhelming mortgage landscape.
So, don’t just dive into house hunting aimlessly! Get pre-approved and arm yourself with crucial information that lets you know exactly what’s in your financial wheelhouse.
The Benefits of Pre-Approval
One of the biggest perks I found with pre-approval is that it strengthens your position as a buyer. Sellers are much more inclined to take your offer seriously when they see you’ve got that pre-approval letter in hand. It’s like waving a shiny badge that shows you’re ready to roll!
Additionally, pre-approval can speed up the home-buying process itself. Instead of waiting and wondering how much you can borrow while making offers, you’ve already got the green light. This could save you a lot of stress down the road. Plus, knowing your budget keeps you from falling in love with homes that are out of reach!
Lastly, pre-approval can provide insight into the types of loans available to you. The lender will discuss various options and terms that suit your financial situation, making it easier to choose the right mortgage later on.
Key Factors Lenders Consider
Now you might be wondering what exactly lenders look at during this process. For starters, your credit score has a major impact on your pre-approval status. Generally, the higher your score, the better your chances of securing a favorable loan.
Another important factor is your income. Lenders want to see that you have a steady income and the capacity to repay the loan. They’ll often ask for documentation like pay stubs and tax returns to get a solid grip on your financial situation.
Lastly, don’t forget about debts! Lenders look closely at your debt-to-income ratio—how much of your income goes towards existing debts compared to how much you could feasibly pay for a mortgage. It’s a balancing act, but it’s super important to nail this part, or it could affect your pre-approval process.
2. Gather the Necessary Documents
Identification and Personal Info
When I started gathering documents for my mortgage pre-approval, I felt like I was prepping for an important exam! The first step is to provide identification and some personal information. Generally, this includes a valid photo ID and your Social Security number.
These pieces of information help the lender verify your identity. Trust me, having everything in order saves you from any last-minute stress. So, keep your ID handy, and make sure your Social Security details are correct!
Also, keep in mind that having accurate information on your application can speed up the review process. So check twice before you submit!
Financial Documents
Next up are your financial documents. Lenders typically require recent bank statements, proof of income, and tax returns from the past couple of years as a part of their assessment. When I did this, I gathered up my bank statements and made sure everything was updated—no dusty old records!
Having all this documentation in one tidy spot upfront makes it easier for your lender to review your financial health. Plus, it’ll show that you’re organized and serious about obtaining that mortgage.
Also, don’t forget about any additional sources of income. Side gigs or passive income streams can make a difference in your application, so be ready to disclose that info too!
Credit Score Check
Okay, let’s talk credit! Before applying, I highly recommend you check your credit score. It’s not just for the lenders; it’s for your own peace of mind. You want to know where you stand before they dive into your finances.
Once I reviewed my credit report, I made sure to correct any inaccuracies, which can happen more often than you’d think. If there are any mistakes, getting them fixed before the lender looks can prevent headaches later.
And if your score isn’t where you want it to be, consider taking a few months to improve it. You could pay down debt, make timely payments, and avoid taking on new loans. Every little bit counts in improving that all-important score!
3. Shop Around for Lenders
Do Your Research
One of the most fun parts of getting pre-approved was shopping around! You’re going to want to research different lenders to find the best fit for your financial situation. Each lender can offer different loans, rates, and terms, which can make a massive difference over time.
Start by checking online reviews and asking friends or family for recommendations. I found that hearing about others’ experiences helped me feel more confident in my choices. Trust me, a little legwork here could lead to significant savings!
Moreover, don’t hesitate to visit local banks and credit unions, as they often have competitive rates and personalized service. This can be especially useful if you have a solid relationship with them, making it easier to get answers to your questions!
Compare Rates and Terms
Once you have a list of potential lenders, it’s time to dig into interest rates and terms. I remember sitting at my kitchen table comparing the numbers. It’s key to look for the best rates because even a slightly lower percentage could lead to thousands of dollars in savings over time.
Don’t just stop at interest rates, though! Make sure you understand all fees involved, like origination fees or closing costs. Ask the lender about every single fee—they should be transparent about what you’re signing up for.
While you’re comparing, take note of the loan types that each lender offers. Do you need a conventional loan, an FHA loan, or something else? Knowing the options lets you evaluate what’s best for you and your financial goals.
Ask Questions
Once you narrow down your choices, it’s time to have conversations with lenders. I found this to be a pivotal moment! Make a list of questions—don’t be shy! Ask about rates, loan types, and the process from start to finish. You want to ensure that you feel comfortable with your lender and how they communicate.
https://Credit411USA.com
The way a lender handles your questions can say a lot about their service. Are they knowledgeable? Friendly? For me, it was important to feel a personal connection. Buying a home is a huge step, and having that trust in your lender makes all the difference!
Also, be sure to ask about the estimated timeline for getting pre-approved. It’s helpful to know when you should expect to hear back so you can plan your next steps.
4. Submit Your Application
Final Checks Before Submission
Before hitting “submit,” make sure everything in your application looks good. I found it super helpful to take a step back and review all my documents and entries. Double-check that the numbers match and that everything is spelled correctly!
Your application is like the first impression for your lender. You want it to be polished and professional! Last-minute checks can save you from delays or errors that could hold up the process later.
Moreover, be prepared for the potential of follow-up questions. Lenders may reach out for additional information, so having a good file system can help you find whatever they need quickly.
What to Expect After Submission
Once your application is in, you might feel a sense of relief—but don’t get too comfortable just yet! After submitting, lenders usually take a few days to a week to review your application and documentation. They may also carry out an appraisal of your finances to determine the final figure you’ll be pre-approved for.
This waiting period can be a bit nerve-wracking, but keeping busy can help your mind off things! Remember, patience is key during this stage. If you’ve done your homework well, then you’re set for good news.
In the meantime, keep your finances stable. Avoid making any big purchases or taking on new debts while waiting for that golden pre-approval letter!
Receiving Your Pre-Approval Letter
If everything checks out, congratulations! You’ll get your pre-approval letter, which outlines how much the lender is willing to loan you. When I received mine, it felt like I’d crossed a significant milestone! This letter is essential as it shows sellers you’re a serious buyer.
It’s also vital to read over the letter carefully. Make sure you understand the terms and how long the pre-approval is valid. Usually, these letters are valid for about 60 to 90 days, but it’s good to clarify with your lender.
Now that you have your golden ticket, you can confidently start house hunting and make offers without hesitation!
5. Start House Hunting!
Set Your Budget
With your pre-approval letter in hand, it’s time to set your budget! Having that number gives you a solid foundation to work with, but you should also consider other expenses like property taxes, insurance, and maintenance. I quickly realized that what I could afford wasn’t just about the mortgage payment; it’s about the full picture.
Take a moment to sit down and outline your financial limits. This includes comfortable monthly payments that won’t stretch your budget too thin. It’s so easy to get caught up in the excitement of house hunting, but being clear about your budget helps prevent heartbreak down the road.
After doing this, I found that it also narrowed down my focus. It made the process so much easier knowing exactly what I was looking at financially!
Find a Real Estate Agent
Having a reliable real estate agent is a game changer in this process. They can provide insight into the current market, help you find properties that fit your budget, and negotiate on your behalf. It’s like having a secret weapon in your corner!
When I was searching, I took the time to interview a few agents to find the right fit. I wanted someone who understood my needs and who I felt comfortable working with. Trust me, it makes a world of difference!
Your agent can also help you understand what to look for in homes and what potential red flags may be. With their support, you’ll feel more confident as you dive into this exciting adventure!
Start Viewing Homes
Now comes the fun part—viewing homes! With your pre-approval letter and a real estate agent, the world is your oyster. This stage is where you’ll begin to discover what you love and what you can do without in a home.
When I started my viewings, I made a checklist of must-haves versus nice-to-haves. This helped to keep me focused and grounded. It’s easy to fall in love with a place that may not fit your long-term goals, so having that comparison list can be a lifesaver!
Lastly, be open-minded during this exploration. Sometimes a place that doesn’t seem perfect can end up being a diamond in the rough. Give each viewings a chance, and most importantly, enjoy the journey of finding your new home!
Frequently Asked Questions
1. What documents do I need for mortgage pre-approval?
To get pre-approved, you typically need identification, proof of income, recent bank statements, and your social security number. Lenders may also want to see your tax returns from the past few years!
2. How long does the pre-approval process take?
The pre-approval process can vary, but it generally takes anywhere from a few days up to a week. Rates of approval can depend on how quickly you provide the necessary documentation!
3. Will my credit score affect my pre-approval?
Absolutely! Your credit score is one of the key factors lenders look at when determining your pre-approval amount. A higher score can lead to better rates and loan terms!
4. Can I get pre-approved if I have bad credit?
It can be more challenging, but it’s not impossible. You may still qualify for certain loans or programs, but it’s best to discuss your situation directly with lenders for personalized advice.
5. How long is a pre-approval letter valid?
Most pre-approval letters are valid for 60 to 90 days, but this can vary by lender. Be sure to ask about the validity period when you receive your letter!
https://Credit411USA.com